Open any mid-sized online casino and you will find thousands of games from dozens of studios, all playable through a single account and a single wallet. That convenience is not an accident, and the casino itself did not integrate each of those studios one by one. Behind the scenes sits a piece of business-to-business infrastructure most players never think about: the game aggregator. It is the connective tissue of the modern iGaming industry, the layer that lets a three-person startup casino launch with more titles than a decade-old brand, and understanding how it works explains a great deal about why the online casino market looks the way it does — why the same games appear everywhere, why new studios scale so quickly, and why operators’ game libraries change almost weekly.
What a game aggregator actually does
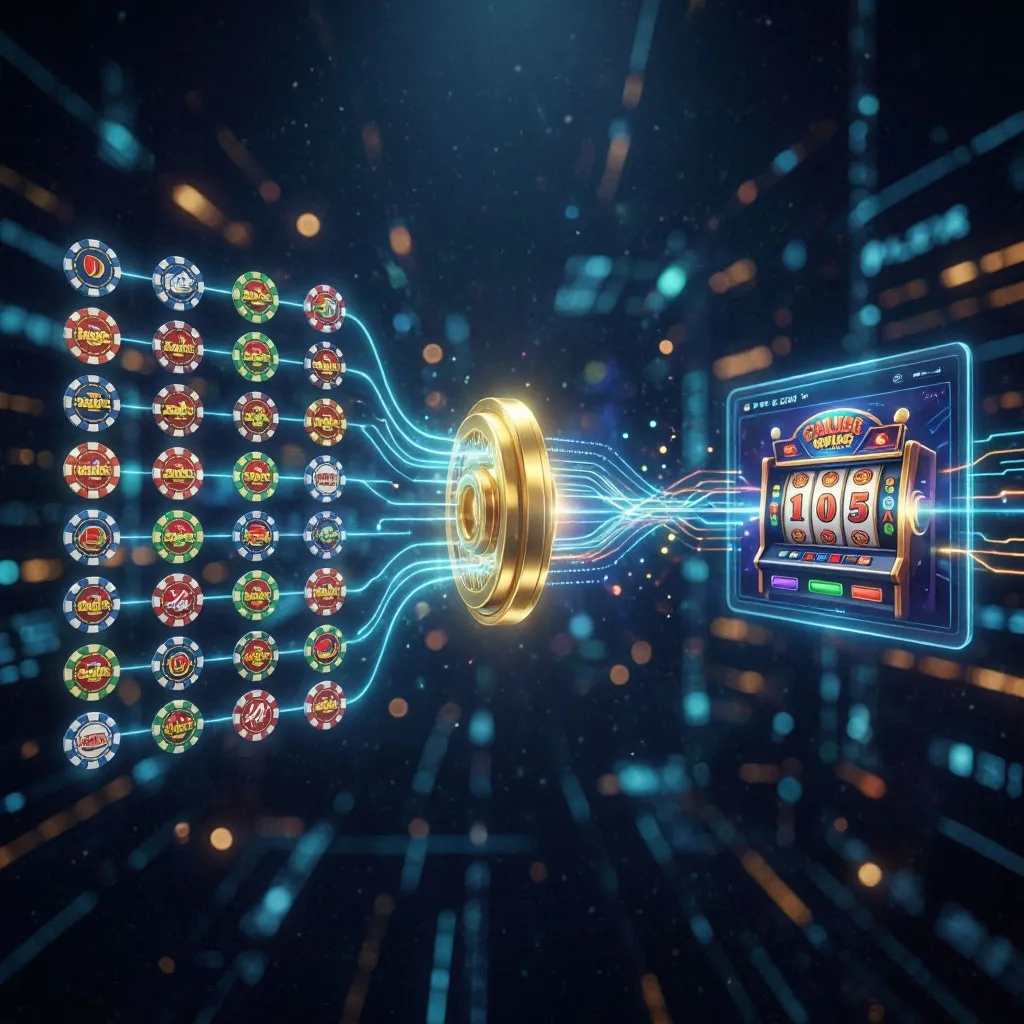
A game aggregator is a platform company that builds and maintains connections — usually via APIs — between game studios and casino operators. A studio makes its slots, live tables or crash games available through one integration into the aggregator’s system; an operator connects once to the aggregator and gains access to the entire catalogue of studios already on board. Rather than a web of individual connections, each with its own contracts, technical quirks and certification requirements, the market runs through a hub.
The analogy that fits best is a streaming marketplace or an app store: content creators publish once and reach every storefront, while storefronts add a whole content ecosystem with a single agreement. In iGaming terms, the aggregator handles the technical plumbing, the commercial relationships and much of the regulatory heavy lifting between the two sides. It makes money on both ends, typically taking a revenue share on the turnover or net gaming revenue that flows through its connections.
The model exists because direct integration is expensive on both sides. A studio that wants to reach a hundred casinos would otherwise negotiate a hundred contracts, build to a hundred different API specifications, re-certify its games in dozens of jurisdictions and maintain a hundred live environments. An operator that wants a hundred studios would face the same costs in reverse. The aggregator collapses both problems into one: one contract, one specification, one certification pipeline, multiplied across the whole network it serves.
The technical machinery underneath
The visible product of an aggregator is a game lobby; the invisible product is a stack of systems that make the lobby trustworthy and functional. When a player spins a slot at a casino connected through an aggregator, a chain of events fires in milliseconds, each link owned by a different company:
- The player’s action reaches the casino front end, which sends a request through the aggregator’s API toward the game provider.
- The provider’s game server resolves the spin, generates the outcome on its certified random number generator and returns the result plus the payout amount.
- The unified wallet layer settles the transaction, debiting or crediting the player’s balance at the casino in real time, regardless of which studio produced the game.
- The aggregator logs, monitors and reports the transaction, feeding both operator dashboards and studio-side revenue reports from the same data.
The unified wallet is the piece that makes the whole model possible. Because the player’s money lives at the casino rather than at each studio, every game — from any provider, on any aggregator connection — debits and credits the same balance. This is why you can switch from a live roulette table to a Megaways slot without transferring funds, and it is why wallet quality, error rates and reconciliation accuracy are the metrics by which aggregators are judged most harshly. A failed transaction or a stuck round is not a technical footnote in this industry; it is a player complaint, a support ticket and, if frequent, a lost contract.
Around that core sit the supporting systems: geo-blocking and compliance filtering that only serve games licensed in the player’s jurisdiction, real-time monitoring that flags downtime or unusual behaviour, bonus and promotion tooling that lets operators run free spins across mixed catalogues, and analytics that show an operator which studios actually earn money in its lobby.
The commercial model behind the plumbing
Aggregation is a business before it is a technology, and its economics explain the shape of the industry. Understanding where the money flows makes clear why aggregators push so hard for both new studios and new operators. The main components of the business model look like this:
- Revenue share on net gaming revenue — the standard arrangement, where the aggregator keeps a percentage of what connected games earn, set by contract with each side.
- Tiered or fixed fees — some operators pay setup or monthly platform fees, particularly when they need custom work, dedicated environments or priority support.
- Certification and compliance services — aggregators often manage the licensing paperwork and testing lab coordination for games entering regulated markets, charging studios for the pipeline.
- Marketplace positioning — premium lobby placement, homepage features and bespoke campaigns are increasingly sold separately, adding a merchandising layer on top of pure distribution.
For studios, the calculus is reach versus margin. Direct integrations with the largest operators keep a bigger slice of revenue in-house but take months of engineering and legal work per partner. An aggregator delivers immediate access to hundreds of operators at once at the cost of a thinner margin on every bet. For operators, the calculus is breadth versus differentiation — a fact that shapes their choices more than anything else in the aggregator relationship.
What operators gain, and what they trade away
The case for aggregation is easiest to see from an operator’s chair. Launching a casino without an aggregator is a project measured in years and dozens of personnel; launching with one is measured in months. The practical advantages run through every department of the business:
- Speed to market — a full multi-studio library can go live within weeks of signing, because the integrations already exist.
- Cost efficiency — one commercial and technical relationship replaces dozens, cutting both upfront engineering and ongoing maintenance overhead.
- Regulatory leverage — aggregators maintain compliance data, certification status and market restrictions across their catalogue, so entering a newly regulated market often becomes a configuration task rather than a legal project.
- Negotiating simplicity — promotions, free spin campaigns and new-game launches can be coordinated across studios from one interface instead of bilateral negotiations with each provider.
- Discoverability — smaller studios that an operator might never have heard of arrive bundled in the catalogue, filling niche categories the operator would struggle to source directly.
The trade-offs are just as real. Aggregator fees sit between the operator and the studio’s own margin, which is why the biggest operators still integrate flagship studios directly — the volume justifies the economics, and exclusive content is a genuine competitive weapon. An operator relying entirely on one aggregator inherits that platform’s library, which means its lobby increasingly resembles every other casino on the same feed. Downtime at the aggregator level becomes downtime for the operator, and switching costs can be substantial once promotions, bonuses and reporting are built around one platform’s tooling. Mature operators typically respond with a hybrid: an aggregator for long-tail breadth plus direct integrations for the studios that define their brand.
Aggregators versus direct integrations versus white labels
Because the terms are used loosely across the industry, it helps to draw the boundaries precisely. The three models overlap in the market but differ in what they move and who bears the cost.
| Model | What it moves | Best suited to | Main drawback |
|---|---|---|---|
| Direct integration | One studio’s games, operator-built | Flagship content at high-volume brands | Months of work and cost per studio |
| Aggregation | Hundreds of studios through one API | New or scaling operators wanting breadth | Margin layer and similar libraries everywhere |
| White label / turnkey | Entire casino platform plus aggregation | Entrepreneurs launching without in-house tech | Least control over product and differentiation |
Reading across the models, the pattern is a trade between control and speed. Direct integrations maximise both control and cost, white labels minimise both, and aggregation sits deliberately in the middle — which is exactly why it has become the default architecture for most of the market. A single operator commonly runs all three at once: a turnkey front end for one brand, direct deals with its headline studios and an aggregator filling out the catalogue beneath them.
How the aggregator market has consolidated
The aggregation space began as a scruffy field of small middleware companies in the early online-casino years and has since consolidated dramatically. SoftSwiss and its GameHub product, Slotegrator’s API Grator (marketed as APIgrator), EveryMatrix’s CasinoEngine, SOFTSWISS’s aggregation stack and ecosystem players like GrooveGTS and Hub88 now move enormous volumes of the industry’s games, and several have been absorbed into larger groups through acquisition. Meanwhile, the biggest studios — Pragmatic Play, Evolution, Playtech — operate their own de facto aggregation through dedicated distribution arms that bundle their own catalogue with third-party content, blurring the line between studio and aggregator entirely.
That consolidation has consequences worth understanding. Aggregators increasingly compete not on the number of studios they carry — thousands of games are available from anyone — but on reliability, compliance depth, data tools and the commercial intelligence they can offer operators. Game count has become a commodity; the differentiators are uptime, certification coverage and whether the platform helps an operator make money rather than merely offering it games.
What this means for players
Players rarely think about aggregation, but they experience its effects constantly, and knowing the mechanism sharpens how you judge a casino. The practical signals are straightforward:
- Same games everywhere — if a casino’s lobby mirrors competitors, it almost certainly runs through a major aggregator feed, and its library offers no real differentiation.
- Featured placement is commercial — prominently positioned new releases often reflect paid promotion through the aggregator’s merchandising tools, not an editorial recommendation by the casino.
- Shared jackpots follow the feed — network jackpots work across casinos because every connected operator draws from the same provider infrastructure.
- Single-wallet breadth — the ability to hop between dozens of studios without separate balances is the unified wallet at work, and a sign the operator leans on aggregation rather than bespoke integration.
None of these observations makes an aggregator-fed casino worse. The model has genuinely democratised access to quality content, letting small operators offer world-class games and letting small studios reach global audiences. It simply means that a large library is no longer evidence of a strong casino on its own — the platform around the games, the payments, the support and the licensing now carry the differentiation that game volume once did.
Where the aggregation layer is heading
The next phase of aggregation looks less like plumbing and more like intelligence. Platforms are layering personalisation engines onto their catalogues, letting operators serve different lobbies to different player segments from the same underlying feed. Bonus tooling is deepening, with achievement systems, tournaments and gamification spanning studios that never built those features themselves. Compliance tooling is becoming a bigger selling point as new regulated markets open, because certification coverage is one of the few things that cannot be copied quickly. And with the rise of crash games, social betting and other non-traditional formats, aggregators are extending beyond classic slots into categories that traditional distribution never covered.
The steady state, in all likelihood, is the one already emerging: aggregation as the invisible default that powers most of the market, direct integrations as the premium layer where big brands and big studios keep their edge, and players enjoying a breadth of content that would have been unthinkable for a small casino a decade ago. The aggregator will remain one of those industry layers nobody talks about — precisely because it works so quietly well.